

Debt Payoff Planner & Tracker
Easily get a plan and stick to it - OxbowSoft LLC
- 4.5
- 1.23K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
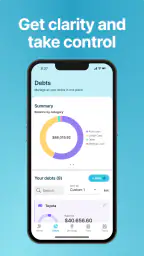
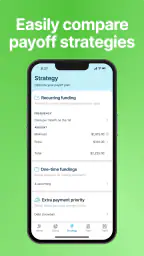
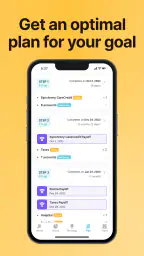
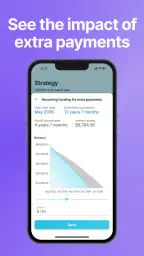
Debt Payoff Planner & Tracker Pros and Cons
Pros
- Clear payoff timelines make debt progress easy to understand.
- Supports multiple debt accounts in one organized dashboard.
- Useful reminders can help maintain consistent repayment habits.
- Flexible payment planning suits different repayment strategies.
- Progress tracking can provide motivation over time.
Cons
- Advanced planning tools may require a paid subscription.
- Manual balance updates can become tedious for active accounts.
- Results depend on entering accurate interest rates and balances.
- Limited features may be available without creating an account.
- It does not make payments directly to lenders.
 Analysis by All-app
Debt payoff is rarely difficult because people do not understand that they owe money. The harder part is keeping several balances, interest charges, due dates, and competing priorities in view without feeling overwhelmed. I found Debt Payoff Planner & Tracker most useful as a focused finance app for turning that vague pressure into a visible plan. It does not try to be a complete banking replacement; its purpose is narrower and, in my opinion, more practical: help you organize repayment, follow progress, and stay motivated.
The app is free to install and is suitable for Everyone, with optional in-app purchases ranging from $6.99 to $41.99 per item. It comes from Easily get a plan and stick to it - OxbowSoft LLC, and its long-running presence is reflected in a release date of January 8, 2015. The current version is 2.54 and it works on Android 6.0 or later. With a 4.5 average from around 4.7 thousand ratings and more than 500 thousand installs, it has clearly found an audience among people who want a dedicated debt payoff planner rather than another general budgeting dashboard.
How the app feels to read and navigate
My first impression is that the app’s focused purpose helps with navigation. Instead of asking me to learn a broad financial system with investments, bank feeds, spending categories, and account rules, it keeps attention on debts and the path toward clearing them. That narrower structure matters when I am already stressed: I can open the app with one question in mind—what should I pay and how is the plan moving?
The visual experience is best suited to someone who is comfortable reading standard mobile screens and entering financial details manually. The important information is naturally numerical, so users need to distinguish balances, payment amounts, and progress indicators without rushing. I recommend taking time during the initial setup rather than trying to enter every account while distracted. A small input mistake can make a repayment projection less useful, even if the app itself is easy to operate.
For readers who prefer a calm, step-by-step approach, the app’s limited scope is a strength. I would prepare a short list of debts before opening it: the lender or account name, current balance, interest information when available, minimum payment, and the amount I can realistically add. Having those details nearby reduces repeated switching between a statement, a calculator, and the app. It also makes the resulting plan feel connected to real household finances instead of being a rough guess.
The app is not the kind of tool I would choose for someone who wants every financial activity visible on one home screen. A full budgeting service may be easier for users who think in terms of income, bills, subscriptions, and spending categories first. Debt Payoff Planner & Tracker makes more sense after the debts have been identified and the user wants a dedicated place to concentrate on repayment.
Readable progress is more useful than financial decoration
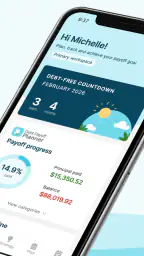
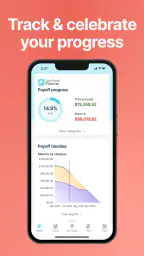
One of the better design choices here is the emphasis on progress rather than financial entertainment. Debt can feel static when I look only at statements: the balance is still there, and the next payment is still waiting. A planner gives each payment a place in a larger sequence. That change in perspective can make a routine transfer feel like a measurable step instead of another monthly obligation.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would still avoid treating any projected finish date as a promise. Interest, new charges, missed payments, changing income, and altered payment amounts can all affect the outcome. The app is most valuable when I revisit the plan after a meaningful change, not when I assume the first version will remain accurate forever. That is an important reading habit for anyone who finds forecasts reassuring but may overlook the conditions behind them.
For people with attention difficulties, I see a useful but limited workflow: update the plan on a fixed day, check only the debts that changed, and record any extra payment immediately. This turns the app into a short recurring task rather than an open-ended financial project. I would not expect the tool alone to create reminders, motivation, or accountability unless those functions are clearly available in the version being used, so pairing it with a calendar routine or a trusted person may be sensible.
Motor, sensory, and situational considerations
Debt planning involves more than visual clarity. Some users may have limited dexterity, tremors, fatigue, or difficulty with prolonged typing. Manual financial entry can become the main obstacle, particularly during setup. I found it more practical to enter information in short sessions, verify each account before moving on, and avoid making changes while walking, commuting, or handling other tasks. A focused app cannot remove the physical effort required to collect accurate figures.
People with low vision or light sensitivity should adjust their device settings to whatever display options work best for them and test whether the app remains comfortable during longer sessions. I would not describe the app as having a particular accessibility certification or assume that every visual preference is supported. The safer approach is to install it on the intended device and check text comfort, contrast, touch targets, and screen behavior before committing to a paid option.
Users who rely on screen readers or alternative input methods should also test the complete journey rather than only the opening screen. The important question is whether account labels, values, controls, and progress information are announced in a meaningful order. Because debt planning depends on interpreting several related numbers, partial compatibility would not be enough for me. I would want to confirm that the whole process—from adding a debt to reviewing the plan—can be completed without needing visual assistance.
Hearing differences are less central to this type of app than they would be in an audio-led product, but alerts and feedback can still matter. Anyone who does not reliably notice sounds should not depend on audio alone for a payment routine. I prefer a written or calendar-based backup for due dates anyway, because a payoff planner is not a substitute for checking the actual lender account and confirming that a payment was processed.
A realistic household workflow
Imagine a person with a credit card balance, a personal loan, and a store account. Their income arrives every two weeks, while the bills fall on different dates. I would begin by entering each debt carefully, then compare the planned payment with the amount that remains after rent, utilities, food, transport, and a small emergency buffer. The key decision is not simply which debt can disappear fastest; it is whether the payment plan can survive an expensive week.
After payday, that person could open the planner, record the payment they actually made, and review how the overall path changed. If an unexpected repair reduces the extra payment, the honest move is to revise the plan rather than pretend the original target still applies. This is where I think the app can support motivation without encouraging unrealistic promises: progress remains visible, but the user stays responsible for updating the assumptions.
A less obvious benefit is that the planner can help couples or family members discuss debt using a shared sequence instead of scattered statements. One person can gather the numbers while another checks whether the proposed payment fits the household’s cash flow. That does not solve disagreements about priorities, but it gives the conversation a concrete object. I would still avoid storing or sharing sensitive information casually, especially on a device used by several people.
Where it differs from ordinary alternatives
The usual alternative is a spreadsheet. A spreadsheet offers flexibility, custom formulas, and easy export, but it also asks the user to build the logic, protect formulas, and keep the presentation understandable. Debt Payoff Planner & Tracker is appealing when I want a ready-made debt-focused workflow and do not want to maintain a financial model by hand. The trade-off is that a spreadsheet can be tailored to unusual situations more deeply.
Another alternative is a general budgeting app. That route is better when the main problem is overspending, irregular income, or understanding where money goes each month. A debt planner is better when the budget already exists—or is being handled elsewhere—and the immediate need is to decide how repayment should progress. I would use both categories together only if I could keep the figures synchronized; duplicate data entry can become frustrating and create conflicting versions of the truth.
Bank and lender apps are still essential because they show official balances, transactions, payment status, and account notices. This planner should sit beside them, not replace them. I would use the lender’s information as the source for current figures, then use the planner to understand the broader repayment route. That distinction prevents a common mistake: assuming a planning estimate is proof that an account has been paid correctly.
Practical strengths and trade-offs during repeated use
The strongest reason to keep using the app is psychological clarity. A debt plan gives extra payments a purpose, and seeing movement can make it easier to continue when the remaining balance still looks large. For users who respond well to milestones, this is more encouraging than a bare list of minimum payments.
The main friction is the need for accurate, ongoing maintenance. If balances, interest, or payment amounts change and I do not update them, the plan becomes a comforting story rather than a reliable guide. That is not a flaw unique to this app, but it is especially important in a focused planner because there are fewer surrounding tools to catch an inconsistency.
The optional purchases also deserve a deliberate decision. Since the app is free to install, I would start with the basic experience and decide whether the available functions justify spending money for my situation. The purchase range is broad enough that I would read each option carefully before confirming anything. Someone who only needs a simple repayment overview may not need to pay, while a committed user who relies on the app every week may find an upgrade worthwhile if it removes a specific limitation they have encountered.
I also think the app is a poor fit for users seeking automatic financial management. If the preferred experience is to connect accounts, categorize transactions, and have balances update with minimal manual work, a broader financial service may be more convenient. Likewise, someone in serious financial distress may need advice from a qualified counselor or creditor support, not just a tracking tool. A planner can organize choices, but it cannot negotiate terms or determine what a household can safely afford.
Who benefits most, and who should look elsewhere
I would recommend this app to a person with several debts who feels motivated by a visible payoff route. It is also a good match for someone who wants to compare repayment priorities without building formulas from scratch. The free starting point lowers the barrier to trying a dedicated tool, and the Everyone rating makes it broadly approachable from an age-classification standpoint.
I would be more cautious recommending it to someone whose finances change dramatically from week to week. Variable income requires frequent judgment, and a fixed plan can create pressure if it is mistaken for a commitment. In that case, a flexible budget and a larger cash-flow view should come first. I would also steer away anyone who finds manual entry exhausting unless they have help collecting and checking the figures.
For users with cognitive or sensory disabilities, the decision should be based on a hands-on trial rather than the app’s category or reputation. The focused purpose may reduce distraction, but the numerical workload can still be demanding. A trusted support person could help with setup and periodic review, while the user keeps control over the goals and payment decisions. That arrangement respects the app’s strengths without assuming that one interface works equally well for everyone.
My inclusive verdict
After using Debt Payoff Planner & Tracker as a dedicated repayment companion, I see it as a practical middle ground between a blank spreadsheet and an oversized financial dashboard. Its value comes from concentration: debts, payments, progress, and motivation stay together. I especially like it for people who need a clear reason behind each payment and who are willing to keep the figures current.
Its accessibility story is more nuanced. The focused workflow may help users who are overwhelmed by broad finance apps, and short review sessions can make the task easier for people with limited energy or attention. At the same time, manual entry, dense numerical information, and the need to verify compatibility with personal assistive technology remain real considerations. I would not recommend purchasing anything until the basic version feels comfortable on the user’s device and the complete planning process can be followed reliably.
My practical advice is to begin with verified lender statements, enter one debt at a time, choose a payment amount that leaves room for ordinary surprises, and review the plan after every major financial change. Keep using the lender’s own app or website for payment confirmation, and use a separate reminder method if missing a date would cause harm. Those habits make the planner more dependable and reduce the risk of confusing motivation with accuracy.
Overall, I would recommend it to a friend who wants a straightforward debt tracking app and is comfortable taking an active role in maintaining the plan. I would not present it as a complete financial solution, an accessibility guarantee, or a replacement for professional help. Used within its proper limits, however, it can turn a scattered set of balances into a manageable routine—and that is a meaningful improvement for anyone trying to regain control of repayment.
Frequently Asked Questions
What is Debt Payoff Planner & Tracker used for?
Debt Payoff Planner & Tracker is designed to help you organize debts, monitor balances, and create a practical repayment strategy. You can enter information such as creditors, interest rates, minimum payments, and due dates, then follow your progress over time. It is useful for people who want a clearer overview of their financial obligations and a structured plan for becoming debt-free.
Does Debt Payoff Planner & Tracker automatically connect to my bank accounts?
The app is primarily intended for planning and tracking debt rather than replacing a bank or credit-card account. Depending on the version and platform, you may need to enter or update balances manually. Users should review the app’s permissions and privacy information before adding sensitive financial details, and they should not assume that every balance or payment is synchronized automatically.
Which debt repayment methods can I use in the app?
Debt Payoff Planner & Tracker commonly supports popular repayment approaches such as the debt snowball and debt avalanche methods. The snowball method focuses on clearing the smallest balance first, while the avalanche method prioritizes debts with the highest interest rates. Comparing both strategies can help you choose between faster motivational wins and potentially lower interest costs.
Can the app calculate how long it will take to pay off my debts?
Yes, the planner can generally estimate repayment timelines by using details such as your current balances, interest rates, minimum payments, and additional amounts you plan to contribute. These projections are only estimates because interest changes, fees, missed payments, and new borrowing can affect the result. Keeping your information updated is essential for more realistic calculations.
Is Debt Payoff Planner & Tracker a substitute for professional financial advice?
No. The app is a budgeting and organization tool, not a licensed financial adviser, credit counselor, lawyer, or tax professional. Its calculations may help you understand possible repayment scenarios, but they do not account for every personal circumstance. If you are facing collection activity, serious financial hardship, insolvency, or legal concerns, consider speaking with a qualified professional before making major decisions.


